
Every rate, fee and limit on this page was checked against Cherry’s own published pages and disclosures on 23 October 2026. Cherry’s disclosures page is dated 12 May 2026. Terms change and vary by practice – confirm your own offer in writing before you sign.
Cherry dental financing lets you split a dental bill into monthly payments after a soft credit check, with plans from 6 weeks to 60 months and APRs from 0% to 35.99%. Approved amounts run from $35 to $65,000, but your dentist decides the ceiling at their practice – which is why you will see $35,000, $50,000 and $65,000 quoted on different sites, all of them technically correct.
Why this page is different. Search this topic and almost every result is either Cherry selling to dentists or a dental practice selling to its own patients. We are neither. This guide is independent, carries no affiliate links, and is built from Cherry’s own disclosure documents – including the one term that Cherry’s marketing does not lead with, and that no dental practice page mentions at all.
The short answer
| Question | Answer |
|---|---|
| What it is | A buy-now-pay-later payment plan for healthcare – not a credit card |
| Who lends the money | Not Cherry. Cherry Technologies Inc. (NMLS #2061234) arranges the plan; lending partners issue it |
| Credit check to apply | Soft only. Cherry states there is no hard credit check at any stage |
| APR range | 0% – 35.99% (capped at 20.99% in Iowa) |
| Terms | 6 weeks (Pay-in-4) up to 60 months |
| Amount | $35 – $65,000, but your practice sets its own ceiling |
| Down payment | Often yes – usually one monthly payment, due at checkout |
| Fees | No origination fee, no prepayment penalty. $15 late fee, $15 NSF fee, 2.99% if you pay by card |
| The catch to check | Whether you are on a true 0% APR plan or a Waived Interest Promotion – they are not the same |
What Cherry actually is – and what it is not
Cherry is a point-of-care payment plan. Your dentist quotes you a price, you apply through a link that belongs to that practice, and if you are approved Cherry pays the practice up front while you repay Cherry over a fixed number of months.
Two things follow from that, and both matter more than people expect.
- It is not a credit card. There is no revolving line, no reusable limit, and no card in your wallet. Each approval covers one course of treatment at one practice. Compare that with CareCredit, which is a Synchrony Bank credit card you keep and reuse.
- Cherry is not the lender. Cherry’s own small print says payment options “are issued by the following lending partners”, and Cherry Technologies Inc. is registered as NMLS #2061234 at 2 Embarcadero Center, San Francisco. The company you pay and the company that holds your loan may not be the same – worth knowing before you need to dispute something.
- Your dentist controls access. You cannot sign up with Cherry independently and take it to any dentist. The practice has to offer it, and the practice sets the maximum it will finance.
Why you see $35,000, $50,000 and $65,000 for the same product
This is the most common point of confusion in this topic, and it is not anyone lying. It is four different numbers that all describe something real:
| Where you will see it | Figure quoted | What it actually means |
|---|---|---|
| Cherry’s homepage disclosure | $35 – $65,000 | The full product range – the authoritative figure |
| Cherry’s dental page | Up to $50,000 | What Cherry markets to dental practices |
| A dental practice page (position 2 on Google) | Up to $35,000 | That practice’s own ceiling |
| A dental blog post (position 11 on Google) | “$10,000 or more” | Understated, and inconsistent with Cherry’s own range |
What to take from it: the number on a dentist’s website is that dentist’s limit, not Cherry’s. If you need to finance a $40,000 full-arch case, the only answer that matters is what your practice can approve. Ask them directly, and do not assume a figure you read elsewhere applies to you.
The four Cherry plan types – and why the difference costs money
People talk about “Cherry’s 0%” as if it were one thing. It is not. Cherry offers at least four structures, and only two of them are genuinely interest-free.
| Plan type | Length | How interest works | What you pay |
|---|---|---|---|
| Pay-in-4 | 4 payments across 6 weeks | Always interest-free. Cherry says everyone approved gets this offer | $0 |
| True 0% APR | Monthly, length varies | Genuinely 0% for qualifying applicants. No interest accrues at all | $0 |
| Waived Interest Promotion | Monthly, with a promo deadline inside the term | Interest accrues. Credited back only if you clear the balance early | Interest, unless you prepay |
| Interest-bearing | 1 – 60 months | Ordinary instalment loan from 5.99% up to 35.99% APR | Interest as quoted |
The first two are straightforward and genuinely good. The fourth is an ordinary loan and at least it is honest about it. The third is the one to understand before you sign anything.
The Waived Interest Promotion: Cherry’s own small print
Cherry’s marketing is direct about CareCredit’s deferred interest, and on the facts it is right to be. But Cherry’s own disclosures describe a promotion that works on a related principle, and it is not mentioned on a single dental practice page we checked.
Under a Waived Interest Promotion, interest accrues on your loan from the start. You may then get a credit for all of it – but only if you satisfy both of these conditions, which Cherry states plainly:
- You make every scheduled payment within 15 days of its due date, and
- You pay the entire principal and all fees off early, on or before the Promotion End Date – a date that falls before your loan’s final scheduled payment.
The second condition is the one that catches people. Cherry’s wording leaves no room for doubt: you will not qualify for the interest credit “by making your regularly scheduled payments”. You have to prepay.
In other words: pay exactly what Cherry asks, every month, on time, to the end of the term – and you pay all of the interest. Here is Cherry’s own published example.
| Amount financed | $1,000.00 |
| Term | 24 months |
| Interest rate | 17.8% |
| Waived Interest Promotional Period | 12 months |
| Scheduled monthly payment | $49.80 |
| Paid after 11 on-time payments | $547.80 |
| Must prepay before the end of month 12 to qualify | $452.20 |
| Interest you pay if you simply follow the schedule | $195.20 |
So on a 24-month plan with a 12-month promotional window, you have to retire a two-year loan in one year to get the interest back. Our own amortisation of those inputs produces $49.83 a month against Cherry’s stated $49.80 – the figures reconcile, which is a good sign the disclosure is accurate. It is the structure that needs explaining, not the maths.
What to do: ask the practice, in writing, whether your plan is a true 0% APR plan or a Waived Interest Promotion. If it is the latter, write the Promotion End Date in your calendar the day you sign and plan to clear the balance before it. That is the same discipline a CareCredit promotional balance needs – see our Cherry vs CareCredit comparison for how the two differ.
The down payment nobody warns you about
Cherry’s example disclosure, which appears on practice sites across the country, describes a $400 plan as costing “$100/month over 3 months at 0% APR with down payment in the amount of monthly payment due at the time of purchase”.
Read that carefully. It is $100 at the dental office on the day, then $100 a month for three months. Four payments of $100, one of which you pay before you walk out. The arithmetic works – $100 plus $300 is the full $400 – but if you arrived expecting to pay nothing today, that is a surprise at the worst moment.
The same pattern applies to Pay-in-4. Cherry’s own illustration shows a $2,000 treatment as $500 every two weeks across six weeks: four payments of $500, with the first due at checkout. Budget for the first instalment on the day of treatment.
Cherry’s fees in full
Cherry markets itself on having “no hidden fees”, and on origination it is true – there is no origination fee and no prepayment penalty, which is genuinely better than many medical lenders. But “no hidden fees” is not “no fees”. From Cherry’s disclosures page:
| Fee | Amount |
|---|---|
| Origination fee | None |
| Prepayment penalty | None – you can pay off early at any time |
| Annual fee | None |
| Late fee | $15.00, if a scheduled payment is not received in full within 15 days of its due date |
| Non-sufficient funds (NSF) fee | $15.00 |
| Paying by credit card or a prepaid/non-traditional debit card | 2.99% processing fee |
| Paying by ordinary debit card or ACH | No processing fee |
Two practical notes. The 2.99% card fee means paying a $3,000 plan by credit card would add about $90 – pay by debit or bank transfer instead. And that 15-day grace period on the late fee is also the window that keeps a Waived Interest Promotion alive, so the two rules interact.
Does Cherry check your credit?
Cherry uses a soft credit check, and says it never runs a hard one. Its own pages state “No hard credit checks, ever”, and that wording is repeated on the practice-facing material Cherry supplies. A soft inquiry does not affect your credit score, so checking what you qualify for costs you nothing.
One correction worth making. A dental blog currently ranking on page one for this term tells readers that “only if you choose to proceed with a payment plan will a hard inquiry be conducted”. That contradicts what Cherry itself publishes. If you have read that elsewhere and it put you off applying, it appears to be wrong – but the sensible move is to ask the practice to confirm it in writing for your specific application, rather than relying on any website, including this one.
Does Cherry report to credit bureaus?
Yes – and this is the part that genuinely affects your credit, not the application. Cherry reports payment activity and plan status to Equifax, Experian and TransUnion. Reporting typically begins after about 30 days, and late payments are reported once an account reaches 30 days past due, with further reporting at 60 days, 90 days and charge-off.
So the two stages are different things, and it is worth holding them apart in your head:
| Stage | What happens | Effect on your credit |
|---|---|---|
| Applying | Soft check only | No effect on your score |
| Paying on time | Reported to all three bureaus | Can help once reporting starts |
| Paying late | Reported from 30 days past due | Can hurt, and a $15 late fee applies |
How likely are you to be approved?
Cherry advertises an “industry-leading” approval rate, and says everyone approved gets an interest-free Pay-in-4 offer. It is a real strength of the product. But be aware the published figure is not consistent, even on Cherry’s own site.
| Source | Figure published |
|---|---|
| Cherry homepage (one section) | ~90% approval rate |
| Cherry homepage (another section, same page) | 80%+ approval rate |
| Cherry dental page | Approve up to 90% of patients for a zero-interest offer |
| Application time | Quoted as both ~35 seconds and 60 seconds on the same homepage |
None of this makes Cherry untrustworthy – these are marketing figures, and most lenders do not publish an approval rate at all. But “up to 90%” is a ceiling, not a prediction about you, and it is not a guarantee. Cherry says its decision weighs credit history, income and debt-to-income ratio alongside your score.
There is no published minimum credit score. Any site quoting you a specific number is guessing. The only way to find out is the soft-check application, which costs your credit nothing.
If you live in Iowa, your rate is capped
This appears only in Cherry’s small print and we found no guide that mentions it: APR for Iowa borrowers is capped at 20.99%, and Iowa applicants are subject to state-specific underwriting.
On a $3,000 plan over 24 months, that cap is worth real money:
| Scenario | Monthly payment | Total interest |
|---|---|---|
| Iowa, capped at 20.99% APR | $154.14 | $699.41 |
| Elsewhere, at the 35.99% ceiling | $177.13 | $1,251.03 |
An Iowa borrower on an otherwise identical worst-case plan pays about $552 less in interest. If you are in Iowa, that is a genuine protection; everywhere else, the 35.99% ceiling is the number to keep in mind when someone says “as low as 5.99%”.
What an interest-bearing Cherry plan actually costs
“As low as 5.99%” is the advertised floor. The ceiling is 35.99%. Since the gap between them is the difference between a cheap loan and an expensive one, here is what a $3,000 treatment looks like across the range:
| APR | 12 months | 24 months | 60 months | Total interest range |
|---|---|---|---|---|
| 5.99% (advertised floor) | $258.19 | $132.95 | $57.98 | $98 – $479 |
| 17.8% (the rate in Cherry’s own example) | $274.75 | $149.48 | $75.85 | $297 – $1,551 |
| 35.99% (advertised ceiling) | $301.37 | $177.13 | $108.38 | $616 – $3,503 |
The pattern to notice: a longer term always lowers the monthly payment and always raises the total. At 35.99% over five years you would repay more than double the treatment cost. If the only number you are shown is the monthly payment, ask for the total.
How to apply
There is no way to apply to Cherry independently and shop it around. The route always runs through a practice.
- Check your dentist offers it. Ask directly, or use Cherry’s provider finder. If they do not offer Cherry, no amount of pre-approval helps you there.
- Get the treatment estimate in writing first. Apply for what the treatment costs, not more.
- Apply through the practice’s own link, QR code or text link. Cherry says the application takes under a minute and gives an instant decision.
- Compare the plan options you are shown. This is the step people skip. You will usually be offered several term lengths – the longest one has the smallest monthly payment and the highest total cost.
- Check the plan type before you accept (see the checklist below), then budget for the down payment on the day.
You will need to be 18 or older, have a US address, a Social Security number, a government photo ID, a bank account for payments, and verifiable income. Cherry may ask for proof of income.
9 terms to confirm before you sign
Everything above condenses into this. Ask for each of these in writing – a practice that cannot answer them is a reason to slow down, not to hurry.
- Which plan type is this? Pay-in-4, true 0% APR, Waived Interest Promotion, or interest-bearing. These are four different products.
- What is the APR? A number, not “as low as”.
- Is there a Promotion End Date, and when? If yes, you are on a waived-interest plan and must clear the balance before that date.
- What is due today? Expect a down payment of roughly one monthly instalment at checkout.
- What is the total I will repay? Not the monthly figure – the total.
- What is this practice’s approval ceiling? Not Cherry’s $65,000 range – theirs.
- What are the late and NSF fees? $15 each at the time of writing, with a 15-day grace period.
- How should I pay? Card payments add 2.99%. Debit or ACH do not.
- Which lending partner holds the loan? Cherry arranges; a partner lends. Worth knowing before a dispute.
Cherry or CareCredit?
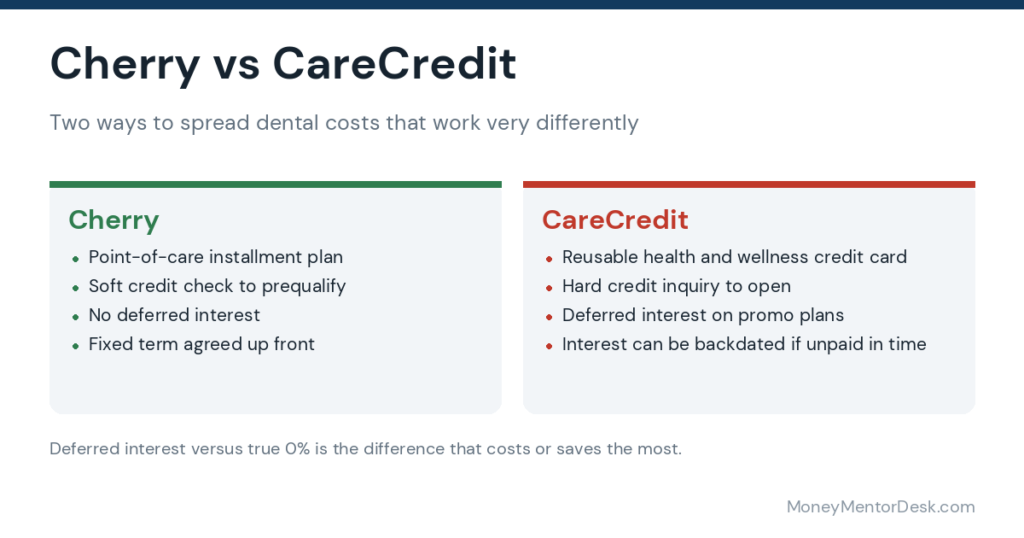
The short version: Cherry is one plan for one treatment with a soft check; CareCredit is a reusable Synchrony credit card whose promotional balances carry deferred interest. Cherry generally approves a wider range of credit profiles. CareCredit is accepted at far more providers and stays open for future care.
Both have an early-payoff trap, which is the part most comparisons miss. CareCredit charges accrued interest if any promotional balance remains at the deadline. Cherry’s waived-interest plans withhold the interest credit unless you prepay ahead of schedule. Neither is a scam; both reward people who clear the balance early and punish people who drift.
We have worked through the numbers on both sides in a full Cherry vs CareCredit comparison, including what deferred interest actually costs cycle by cycle.
If Cherry turns you down
A denial is not the end of the conversation, and it is worth knowing the order to work through rather than accepting whatever is offered next.
- Ask the practice about an in-house payment plan. Many dentists run one and will not mention it unless asked. These often have looser criteria and no credit check.
- Ask about a discount for paying up front, or for staging the treatment across two benefit years.
- Ask whether the practice offers financial assistance. The Consumer Financial Protection Bureau has reported that financing companies market directly to providers and supply them with sales material, and that providers may be disincentivised to explain zero-interest or assistance options first. Asking costs nothing.
- Compare a credit union personal loan. Rates are often well below 35.99%, and the loan is not tied to one practice.
- Be wary of the next product offered at the chair. If you were declined by one point-of-care lender and are immediately offered another, check the APR and the total before agreeing to anything.
Frequently asked questions
Is Cherry dental financing good?
For a Pay-in-4 or true 0% APR plan, yes – it is a genuinely useful product with no origination fee, no prepayment penalty and no hard credit check. For a Waived Interest Promotion or an interest-bearing plan at the upper end of the range, it is an ordinary loan and should be compared against a credit union before you accept it. The product is only as good as the plan type you are given.
What is the minimum credit score for Cherry financing?
Cherry does not publish one. It says its decision considers credit history, income and debt-to-income ratio, not a score alone. Because the application is a soft check, you can find out without any effect on your credit.
How hard is it to get approved with Cherry financing?
Cherry advertises approval of up to 90% of applicants and says everyone approved receives an interest-free Pay-in-4 offer. Those are marketing figures and Cherry publishes both “80%+” and “~90%” in different places on its own site, so treat them as a ceiling rather than a prediction. Approval is not guaranteed.
Does Cherry do a hard credit check?
Cherry states it does not run a hard credit check at any stage. At least one page currently ranking for this topic says a hard inquiry happens when you accept a plan; that conflicts with Cherry’s own published position. Ask the practice to confirm in writing for your application.
What is Cherry’s interest rate?
0% to 35.99% APR, with interest-bearing plans advertised from 5.99%. Iowa borrowers are capped at 20.99%. Your rate is disclosed before you commit – do not accept a plan without seeing it.
How much can I finance with Cherry?
Cherry’s published product range is $35 to $65,000, but the practical ceiling is whatever your dental practice is set up to offer. Different practices advertise $35,000 or $50,000. Ask yours.
Can I pay a Cherry plan off early?
Yes, with no prepayment penalty. On an interest-bearing plan that saves you interest. On a Waived Interest Promotion, paying off early before the Promotion End Date is the only way to get the interest credited back at all.
Where do I log in or contact Cherry?
Account management is through Cherry’s own consumer portal, where you can view your balance, make a payment and pay a plan off. Cherry publishes a customer support line and email address on its disclosures page. We deliberately do not reproduce phone numbers here, because they change – take them from Cherry’s own site.
Independent disclosure
MoneyMentorDesk is not affiliated with Cherry Technologies Inc., is not a Cherry partner, and earns no commission from Cherry or any lender named on this page. There are no affiliate links in this article.
This is general education, not financial advice. We are not a lender, broker or licensed adviser. Rates, fees and terms change, vary by practice and by applicant, and the figures here were correct on the date shown. Our dollar examples are illustrations calculated from published rates using standard declining-balance amortisation, not quotes. Always read your own loan agreement and Truth in Lending disclosure before signing. For neutral guidance on medical financing and deferred interest, see the Consumer Financial Protection Bureau.
Author: Nimra Saleem, MoneyMentorDesk. Rates verified: 23 October 2026 against Cherry’s own published pages and disclosures.
Sources
- Cherry – Disclosures and Loan Definitions (page dated 12 May 2026: $15 late fee after 15 days, $15 NSF fee, 2.99% card processing fee, no prepayment penalty, and the full Waived Interest Promotion terms and worked example)
- Cherry – homepage (APR 0%-35.99%, terms 1-60 months, amounts $35-$65,000, approval rate claims, application time)
- Cherry – dental financing (dental amounts up to $50,000; Pay-in-4 and 0% APR structures; note this page is addressed to dental practices, not patients)
- Cherry – consumer page (soft credit check, credit bureau reporting, eligibility)
- CFPB – Medical Credit Cards and Financing Plans (how these products are marketed through providers)
- CFPB – What is deferred interest?
Pingback: How Much Do Braces Cost Without Insurance? 2026 Cheapest Options - MoneyMentorDesk.com