
Part of our guide: PCP vs HP: 5 Differences and a Worked Cost Example (UK)
A bonus lands, or you’d rather stop paying interest on a car you plan to keep. Early settlement car finance means paying off the rest of your agreement before the term ends. On a regulated agreement it’s a legal right under section 94 of the Consumer Credit Act 1974, and the amount you pay includes a rebate of the interest you’d otherwise have paid later. You ask the lender for a settlement figure, pay it, and the agreement ends.
This guide explains how the settlement figure is worked out, what the lender can and can’t charge, and the steps to take. For how PCP itself works, see what PCP finance is and how it works.
In the US? This guide covers UK agreements under the Consumer Credit Act. US car loans work differently: you ask your lender for a payoff quote with a good-through date. See what a 10-day payoff is and how to calculate your payoff amount.
Can you pay off car finance early?
Yes. Section 94 of the Consumer Credit Act 1974 lets the debtor under a regulated consumer credit agreement pay off the whole balance “at any time”, by giving notice to the creditor and paying what’s owed, less any rebate the law allows.
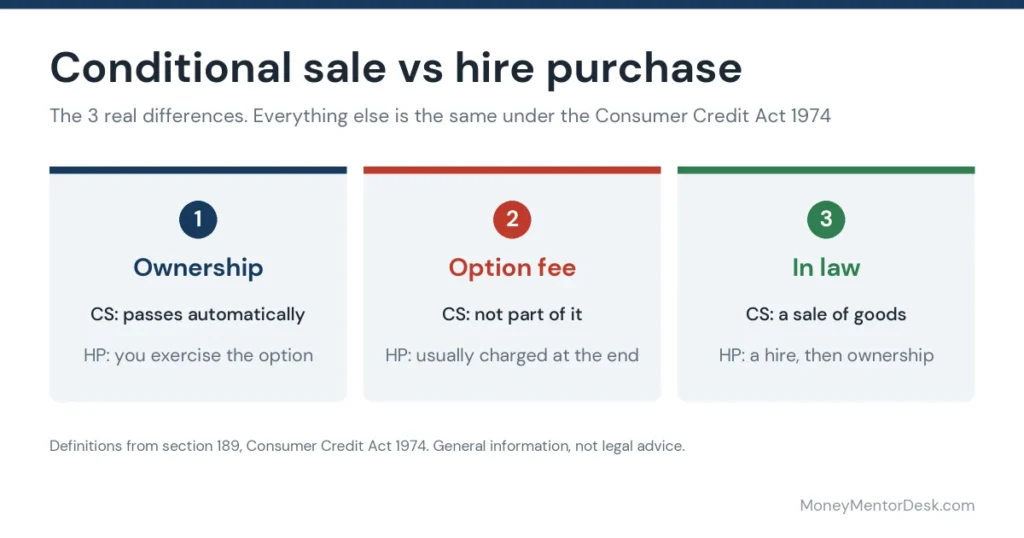
- Hire purchase, conditional sale and PCP agreements that are regulated are covered.
- You can settle in part, not just in full (section 94(3)).
- Your notice doesn’t have to be in writing for car finance. Section 94(6) says notice under the section “need not be in writing” unless the agreement is secured on land.
What is a settlement figure?
A settlement figure is the amount you’d need to pay to clear the agreement on a given date.
- You have a legal right to one. Under section 97, when you ask, the lender must give you a statement of the amount needed to discharge the agreement and show how it’s arrived at.
- It must arrive within 7 working days. Regulation 4 of the Consumer Credit (Settlement Information) Regulations 1983 sets “the period of 7 working days”.
- The request doesn’t have to be in writing (unless the agreement is secured on land), and the lender doesn’t have to answer a new request made less than a month after it last complied with one.
- What the statement shows: the Regulations list the amount without a rebate, any compensatory amount, the rebate, the net amount to pay, the settlement date and how any rebate was calculated.
- Figures have a shelf life. Close Brothers Motor Finance, for example, says its settlement quote “will be valid for 28 days”. Some lenders let you request one online; Stellantis Financial Services says a request made in its online account before 7pm appears within 15 minutes.
How the early settlement rebate works
You don’t pay all the remaining monthly payments. Under section 95 and the Consumer Credit (Early Settlement) Regulations 2004, you get a rebate of the interest that relates to the time after you settle.
In plain English, regulation 4 works out what you owe at the settlement date by:
- growing the amount you borrowed at the agreement’s APR up to the settlement date, then
- taking away every payment you’ve made, each also grown at the APR to that date.
The rebate is the difference between the remaining scheduled repayments and that figure.
Two timing rules make the figure slightly higher than the bare balance:
- The settlement date is 28 days after the lender receives your notice, or a later date you choose, as long as you pay by then (regulation 5).
- A one-month deferral can apply. For credit repaid over more than a year, the lender can treat the settlement date as one month later (or 30 days) when working out the rebate (regulation 6). In effect you pay around one extra month’s interest.
What counts: regulation 3 bases the rebate on sums included in the total charge for credit, so interest and credit-related charges. The exact figure is on your lender’s statement.
Worked example: settling a £25,000 PCP early
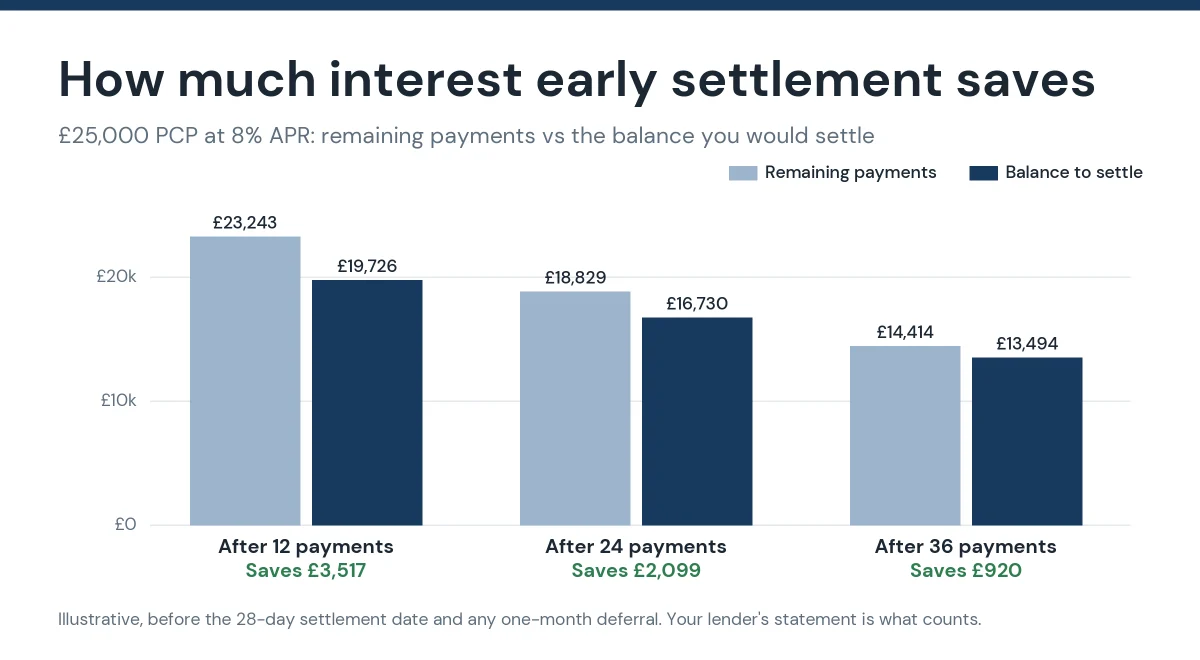
This uses the same car as our PCP guide:
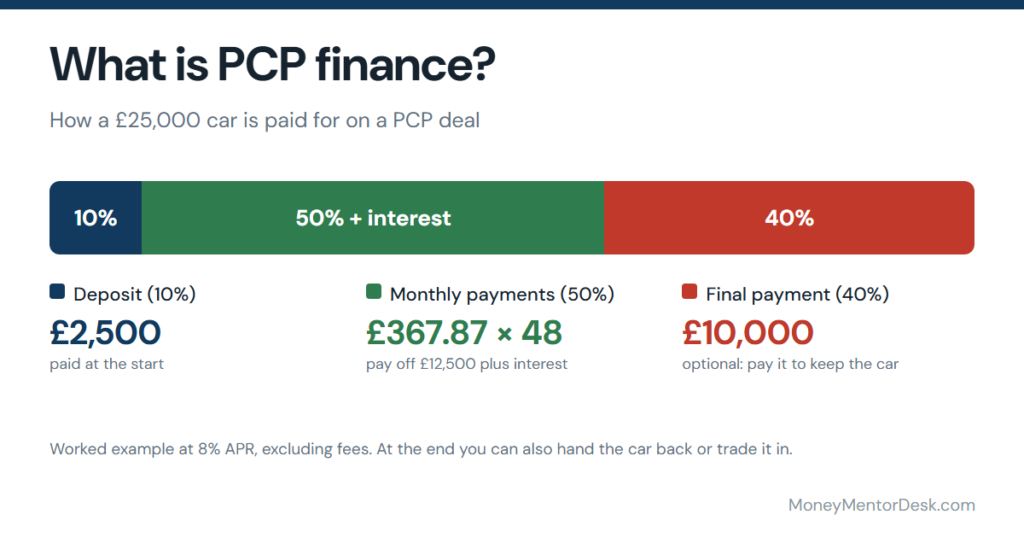
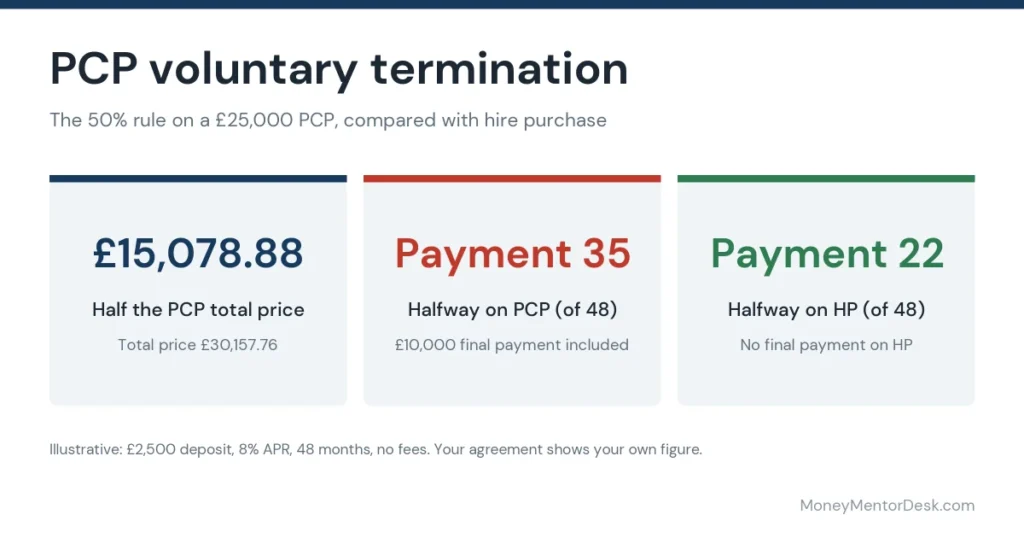
- £25,000 car and a £2,500 deposit, so £22,500 is borrowed
- 8% APR over 48 months
- 48 monthly payments of £367.87 and a £10,000 final payment
The figures are illustrative, not a quote.
| After this many payments | Remaining scheduled payments (incl. £10,000 final payment) | Balance at that date | Interest saved | About one month’s deferral interest |
|---|---|---|---|---|
| 12 | £23,243.32 | £19,725.95 | £3,517.37 | £126.92 |
| 24 | £18,828.88 | £16,729.97 | £2,098.91 | £107.64 |
| 36 | £14,414.44 | £13,494.31 | £920.13 | £86.82 |
Balance calculated at 8% APR as an effective annual rate, before the 28-day settlement date and any one-month deferral. The last column shows roughly what a one-month deferral adds. Your lender’s settlement statement is what counts.
The same car on hire purchase (48 payments of £546.35, no final payment):
- after 24 payments, remaining payments are £13,112.40 and the balance is £12,114.03, saving £998.37
- after 36 payments, remaining payments are £6,556.20 and the balance is £6,289.90, saving £266.30
The saving is bigger early in the agreement, because more of the interest is still ahead of you. On PCP it stays large for longer, because interest keeps building on the £10,000 final payment you haven’t repaid.
Can your lender charge you for settling early?
Only in limited cases. Section 95A lets a lender claim a “compensatory amount” when:
- the agreement has a fixed interest rate, and
- you repay more than £8,000 early in one payment, or in payments totalling more than £8,000 within 12 months.
The charge is capped at the lower of:
- 1% of the amount repaid early if more than a year of the agreement is left, or 0.5% if a year or less is left, and
- the interest you’d have paid between the early repayment and the original end date.
It must also be “fair” and “objectively justified”. Close Brothers Motor Finance reflects this on its settlement page: “Charges may apply for a one-off payment that exceeds £8,000 or for accumulated payments over a 12-month period that exceed £8,000.”
Any compensatory amount must appear on your settlement statement.
Partial early settlement
You can pay off part of the balance instead of all of it. Under section 94(3) to (5):
- Tell the lender you want to make a partial early repayment.
- Pay within 28 days of the lender receiving your notice, or by a later date you give.
- The balance falls by the amount you pay plus any rebate, less any compensatory amount.
Ask the lender in writing whether the part payment will shorten the term or lower your monthly payments, and get the new figures before you pay.
6 steps to settle your car finance early
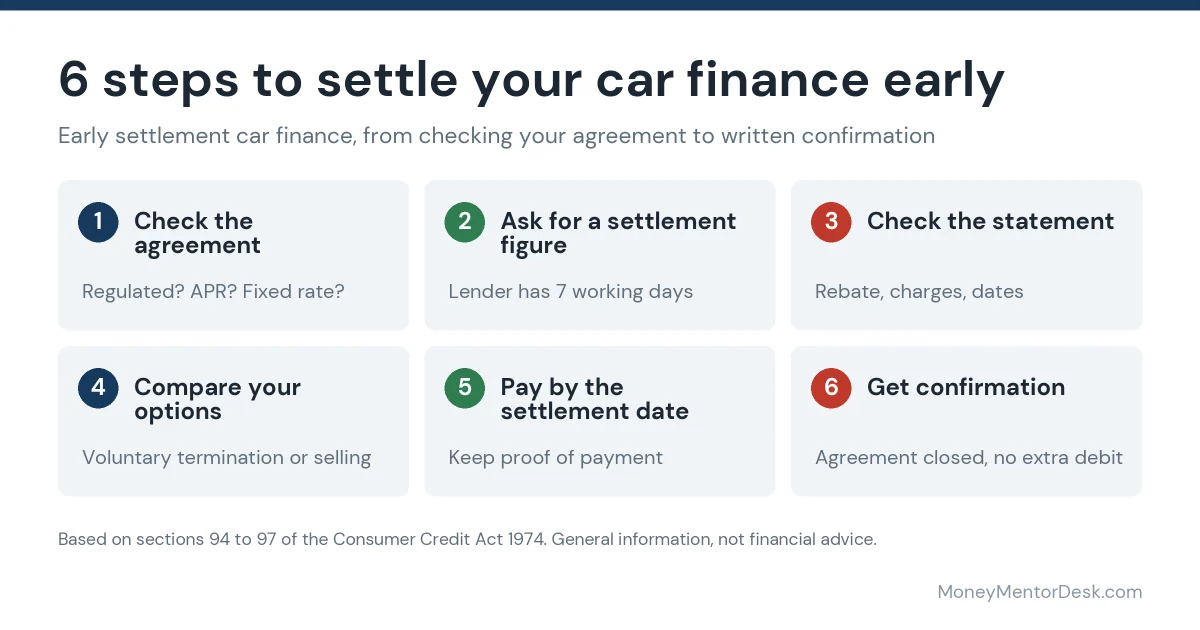
- Check your agreement is regulated and find the APR and whether the rate is fixed. The agreement will show these.
- Ask for a settlement figure. Use the lender’s online account, phone or letter. The lender has 7 working days to send the statement.
- Check the statement. Look at the rebate, any compensatory amount, the settlement date and how long the figure is valid.
- Compare it with your other options, such as voluntary termination or selling the car (see below).
- Pay by the settlement date using the method the lender gives, and keep proof of payment.
- Get written confirmation that the agreement is closed, and check whether a final direct debit has also gone out. Stellantis, for example, says a refund may be due if an instalment was paid after settlement.
Once everything owed is paid, including any option-to-purchase fee on hire purchase or PCP, ownership passes to you.
Early settlement vs voluntary termination vs selling the car
| Early settlement | Voluntary termination | Selling or part-exchanging | |
|---|---|---|---|
| You keep the car? | Yes | No, it goes back to the lender | No |
| What you pay | The settlement figure (balance plus any compensatory amount) | A top-up to half the total price if you’re below halfway, plus arrears and any reasonable-care charge | The settlement figure, often from the sale proceeds |
| May suit you when | You want to own the car and can afford the figure | You owe more than the car is worth and are near or past halfway | The car is worth more than the settlement figure |
See our guide to voluntary termination and the half rule for how that route works, and PCP vs HP for how the two agreements compare.
FAQs
Can you pay off car finance early?
Yes. Section 94 of the Consumer Credit Act 1974 lets you pay off a regulated car finance agreement at any time, in full or in part. You pay the settlement figure, which includes a rebate of future interest under the Consumer Credit (Early Settlement) Regulations 2004.
How long does it take to get a settlement figure?
Your lender must send a settlement statement within 7 working days of your request, under section 97 of the Consumer Credit Act 1974 and the Settlement Information Regulations 1983. Some lenders are faster online. Stellantis Financial Services says online requests made before 7pm appear within 15 minutes.
Do you save money by settling car finance early?
Usually. You get a rebate of the interest for the time after the settlement date. In our £25,000 PCP example at 8% APR, settling after 24 payments saves about £2,099 before timing adjustments. The earlier you settle, the more interest you save.
Is there a penalty for paying off car finance early?
Only in limited cases. A lender can claim a compensatory amount under section 95A if the rate is fixed and you repay more than £8,000 early within 12 months. It’s capped at 1% of the amount repaid, or 0.5% if a year or less is left.
How long is a car finance settlement figure valid?
It depends on the lender, so check the date on the statement. Close Brothers Motor Finance, for example, says its settlement quotes are valid for 28 days. The legal settlement date is normally 28 days after the lender receives your notice.
Do I own the car after early settlement?
Yes, once everything owed is paid. On hire purchase and PCP, that includes any option-to-purchase fee. Ask the lender to confirm in writing that the agreement is closed.
Sources
- Consumer Credit Act 1974, section 94, section 95, section 95A and section 97, legislation.gov.uk, checked 17 September 2026
- Consumer Credit (Early Settlement) Regulations 2004, regulations 3 to 6, checked 17 September 2026
- Consumer Credit (Settlement Information) Regulations 1983, regulation 4 and Schedule, checked 17 September 2026
- Close Brothers Motor Finance: How do I get a settlement quote?, checked 17 September 2026
- Stellantis Financial Services: Early settlement requests and Settling your agreement, checked 17 September 2026
This guide is general information, not financial or legal advice. Your lender’s settlement statement shows the figure that applies to your agreement.
Written by Nimra Saleem for MoneyMentorDesk.com. Last reviewed on 17 September 2026 against the Consumer Credit Act 1974, the Consumer Credit (Early Settlement) Regulations 2004 and the Consumer Credit (Settlement Information) Regulations 1983 on legislation.gov.uk, Close Brothers Motor Finance and Stellantis Financial Services.
Pingback: Conditional Sale vs Hire Purchase: The 3 Key Differences