Part of our guide: What Is a 10-Day Payoff Quote? Auto Loan Payoff Explained
This refinance auto loan calculator shows two numbers that usually disagree: how much a refinance cuts your monthly payment, and how much it changes what you pay in total. Enter your balance, your current payment and the months left, then the APR and term you have been offered.
Whether you call it an auto refinance calculator, a car loan refinance calculator or a refinance car payment calculator, most of them show the monthly saving alone. That is the number that sells the loan, and it is the one that hides a longer term.
Auto Refinance Calculator
See what a refinance saves you each month, and what it costs you over the life of the loan.
| Now | Refinanced | |
|---|---|---|
| Monthly payment | — | — |
| Months remaining | — | — |
| Interest still to pay | — | — |
| Fees and penalties | — | — |
| Rate | — | — |
Educational estimate only, not financial advice. Your current rate is worked back from the balance, payment and months left, so it is an estimate. The comparison assumes level payments and no further fees. Ask the new lender for the APR and the total of payments in writing, and check your existing agreement for a prepayment penalty before you switch.
A lower rate can still cost you more
Take a $18,000 balance with 36 months left and a $560 monthly payment. That works out at about 7.51% APR, and $2,160 of interest still to pay. Now compare three offers, all at a lower rate than you have:
| Offer | New payment | Monthly change | Total cost change |
|---|---|---|---|
| 5.9% over 36 months | $546.78 | $13 less | $476 less |
| 5.9% over 48 months | $421.91 | $138 less | $91 more |
| 5.9% over 60 months | $347.15 | $213 less | $669 more |
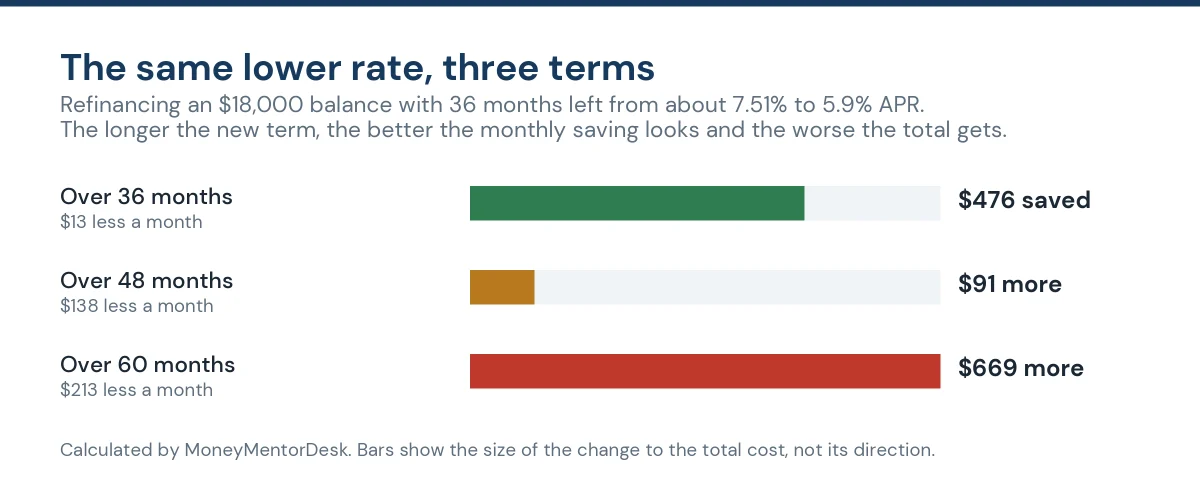
All three cut the interest rate from 7.51% to 5.9%. Only the first one saves money. Stretch the same lower rate over 60 months and the payment falls by $213, which feels like a win, while the total cost rises by $669.
That is not an argument against refinancing. A lower payment can be exactly what you need, and buying breathing room for $669 may be a fair trade. The point is to make that trade knowingly, rather than being shown one number.
How this refinance auto loan calculator works
The calculator works your current rate backwards from three things you already know: the balance, the monthly payment and the number of payments left. The interest you have left to pay is simply your remaining payments minus your balance.
For the new loan it amortises your balance at the offered APR over the offered term, adds any fees or prepayment penalty you enter, and compares the two totals. Because your current rate is inferred rather than taken from your agreement, treat it as an estimate and check it against your paperwork.
Check these before you switch
Before you trust any refinance auto loan calculator, including this one, check six things about the loan you already have.
- A prepayment penalty on your current loan. Refinancing pays off the old loan, so any penalty applies. The CFPB notes that some states prohibit them for certain loans. Our guide to whether you can pay off a car loan early shows where the clause sits in your contract.
- Precomputed interest. If your current loan precomputed the finance charge, settling it early gets you a refund of unearned interest rather than stopping interest, and the refund may be less than you expect.
- The term you are being offered. Lenders often quote a longer term because it produces a better-looking payment. Ask for a quote at your remaining term as well.
- Fees. Title transfer, lien recording and registration fees vary by state. Put them in the calculator rather than ignoring them.
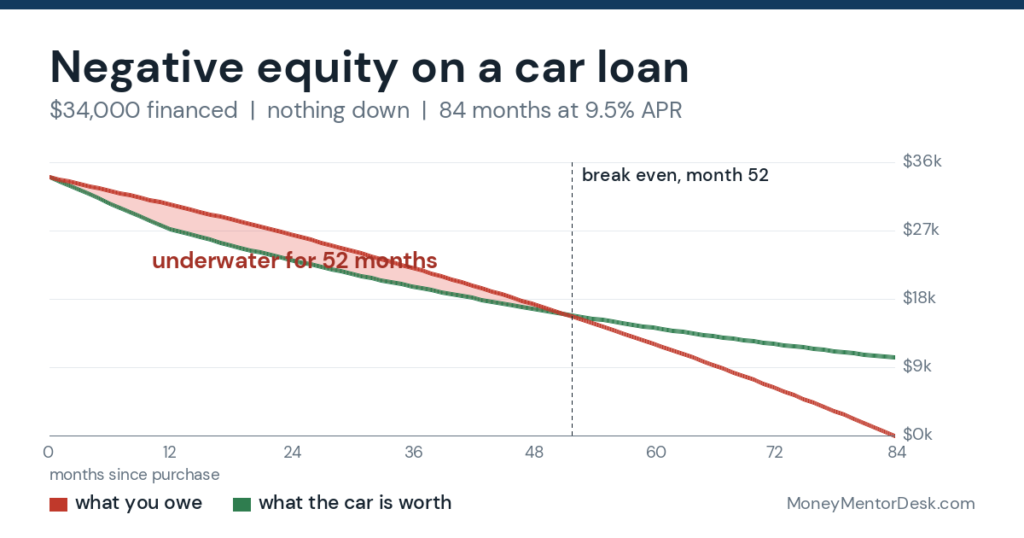
- Negative equity. If you owe more than the car is worth, most lenders will not refinance, and rolling the shortfall into a new loan makes it worse.
- Whether your rate is actually high. Experian put the average used-car APR at 11.19% and new-car at 6.35% in the second quarter of 2026. Our guide to APR on a car loan has the full table by credit tier.
When refinancing an auto loan is worth it
- Your credit has improved since you took the loan out, so you qualify for a materially lower rate.
- Rates have fallen, or you financed at the dealership without shopping around.
- You can take the lower rate without extending the term.
- You need a lower payment to stabilise your budget, and you accept the higher total knowingly.
Refinancing is not worth it when the saving is swallowed by fees, when you are close to the end of the loan and most of the interest is already paid, or when the only way to cut the payment is to add years. Our guide to when to refinance a car loan, and when to wait goes through the timing.
A refinance auto loan calculator only answers half the question. If your aim is to get rid of the loan rather than reshape it, the other side of the coin is paying it down faster. See the early payoff calculator and the car loan payoff guide.
Before the refinance auto loan calculator helps: can you get a better rate?
Refinancing only works if a lender will price you below what you already pay, and that depends almost entirely on your credit tier. Take the same $18,000 balance with 36 months left at about 7.51%, refinanced over the same 36 months at Experian’s Q2 2026 average used-car rates:
| Credit tier | Average APR | New payment | Interest | Against your current loan |
|---|---|---|---|---|
| Super prime (781+) | 6.29% | $549.96 | $1,798.67 | saves $361.33 |
| Prime (661 to 780) | 8.81% | $570.80 | $2,548.97 | costs $388.97 more |
| Near prime (601 to 660) | 13.93% | $614.59 | $4,125.08 | costs $1,965.08 more |
| Subprime (501 to 600) | 19.10% | $660.72 | $5,785.88 | costs $3,625.88 more |
Only the top tier beats a 7.51% loan. At prime, the national average rate is higher than the loan you already have, which is why a refinance offer can arrive looking like a favour and cost you money. Before applying, work out roughly where you sit, and compare against your existing rate rather than against nothing. Our guide to APR on a car loan has the full table by tier for new and used.
Refinancing against simply paying extra
A refinance auto loan calculator answers the offer in front of you. The comparison almost nobody runs is against doing nothing clever at all. On that same $18,000 balance at 7.51%:
| What you do | Loan clears in | Interest | Saving |
|---|---|---|---|
| Nothing | 36 months | $2,160.00 | — |
| Pay $50 a month extra | 33 months | $1,962.55 | $197.45 |
| Pay $100 a month extra | 30 months | $1,798.57 | $361.43 |
| Pay $150 a month extra | 28 months | $1,661.34 | $498.66 |
| Refinance at 6.29%, same term | 36 months | $1,798.67 | $361.33 |
Look at the last two rows. Paying an extra $100 a month saves $361.43. Refinancing to the best average rate in the country saves $361.33. The same money, within a dollar, except one route needs an application, a hard credit check, a new account, title work and possibly a fee, and the other needs a standing order.
That does not make refinancing pointless. It makes it the right tool for one specific job: when your rate is genuinely high for your credit, usually because you financed at the dealership or your credit has improved since. If your rate is already reasonable, extra payments do the same work with none of the friction. Our guide to how to pay off a car loan early covers making sure the extra reaches the principal, which is where that saving actually comes from.
What a lender looks at before refinancing you
Refinance lenders underwrite the car as well as you, which is why applications get declined for reasons that have nothing to do with your credit file. The common limits to check before you apply:
- Loan to value. If you owe more than the car is worth, most lenders will not refinance at all. Get a valuation before you apply.
- The age and mileage of the car at the end of the new term, not today. This is what quietly blocks longer terms on older cars.
- A minimum balance. Many lenders will not write a small refinance, so a nearly-finished loan may not qualify.
- How long you have had the loan. Some require a few months of payment history before they will refinance it.
- The title. The new lender has to take the lien, so anything odd about the title will stall the process.
These vary by lender, so treat them as the questions to ask rather than fixed rules. Asking them first avoids a hard credit check on an application that was never going to complete.
What happens to GAP cover and add-ons
Add-on products are the step most people miss. Refinancing pays off the original loan, and products sold alongside that loan are usually tied to it.
- GAP insurance bought with the original finance normally ends when that finance ends. If you still owe more than the car is worth, you may want cover on the new loan.
- Extended warranties and service plans financed into the original loan may be cancellable for a prorated refund, which can be worth more than the refinance saving.
- Payment protection products usually end with the agreement they were sold against.
Ask the original lender what ends and what refunds, in writing, before the payoff goes through. Our guide to whether GAP insurance is worth it covers the cover itself.
The credit cost of refinancing
A refinance means a hard inquiry, an account closing and a new account opening, all at once. Expect a small, temporary dip.
Rate shopping is treated more kindly than it looks: scoring models group similar inquiries made in a short window so that comparing lenders does not count as repeatedly applying for credit. Do your shopping in a tight block rather than spread over months. The mechanics of how a car loan affects your file are in does paying off a car loan help credit.
How to refinance, step by step
- Get your payoff figure from the current lender, not your app balance.
- Value the car so you know your loan-to-value position before anyone runs a credit check.
- Check your current agreement for a prepayment penalty, using the Prepayment box described in can you pay off a car loan early.
- Gather quotes in a short window, and ask each lender for the APR, the term, the total of payments and every fee.
- Run each quote through the calculator above, at your remaining term as well as the term they offer.
- Confirm what happens to GAP and any add-ons.
- Keep paying the old loan until you have written confirmation it is settled. Payoffs can take days to land, and a missed payment in the gap is reported like any other.
Auto refinance FAQs
What does a refinance auto loan calculator actually tell you?
A good one tells you two things: how much the new loan changes your monthly payment, and how much it changes the total you pay. Most show only the monthly figure, which hides a longer term. On an $18,000 balance with 36 months left, refinancing to 5.9% over 60 months saves $213 a month and costs $669 more overall.
Does refinancing a car loan save money?
Only if the new loan costs less in total, not just per month. On a $18,000 balance with 36 months left at about 7.51%, refinancing to 5.9% over the same 36 months saves $476. The same 5.9% rate over 60 months cuts the payment by $213 a month but costs $669 more overall.
How do I calculate my current car loan interest rate?
Work it backwards from your balance, your monthly payment and the number of payments left. The calculator above does this for you. The interest you have left to pay is your remaining payments minus your balance, so $560 a month for 36 months on an $18,000 balance means $2,160 of interest still to come.
Is it worth refinancing for 1%?
It depends on your balance and how long is left, not on the size of the rate cut. A 1% reduction on a large balance with years to run can be worth hundreds; the same cut with six months left is worth very little, because most of the interest has already been paid. Run both terms through the calculator.
Does refinancing a car loan hurt your credit?
Applying usually causes a hard inquiry, and the old account closes while a new one opens, which can move your score slightly in the short term. The longer-term effect depends on how you manage the new loan.
Can I refinance if I owe more than the car is worth?
Usually not. Most lenders will not refinance a loan that is underwater, and rolling the shortfall into a new loan increases the balance and the interest you pay. Paying the balance down to the car’s value first is the usual route.
Will I be charged a penalty for refinancing?
Refinancing pays off your existing loan, so any prepayment penalty in that agreement applies. The CFPB notes that some states prohibit prepayment penalties for certain loans. Check the Prepayment section of your current contract and enter the figure in the calculator.
Sources
- CFPB: Can I prepay my loan at any time without penalty?, checked 26 September 2026
- CFPB: simple interest vs precomputed interest on an auto loan, checked 26 September 2026
- Experian: average car loan interest rates by credit score (Q2 2026), checked 26 September 2026
- Worked example calculated by MoneyMentorDesk using the standard amortising formula
This calculator is educational and is not financial advice. Ask any lender for the APR and the total of payments in writing before you agree to refinance.
Built and checked by Nimra Saleem for MoneyMentorDesk.com on 26 September 2026.