
Part of our guide: What Is a 10-Day Payoff Quote? Auto Loan Payoff Explained
Does paying off a car loan help credit? Over time, usually yes, because the account keeps reporting as paid on time. In the short term it can cost you a few points, and only for one specific reason: the loan was the last active installment account on your file.
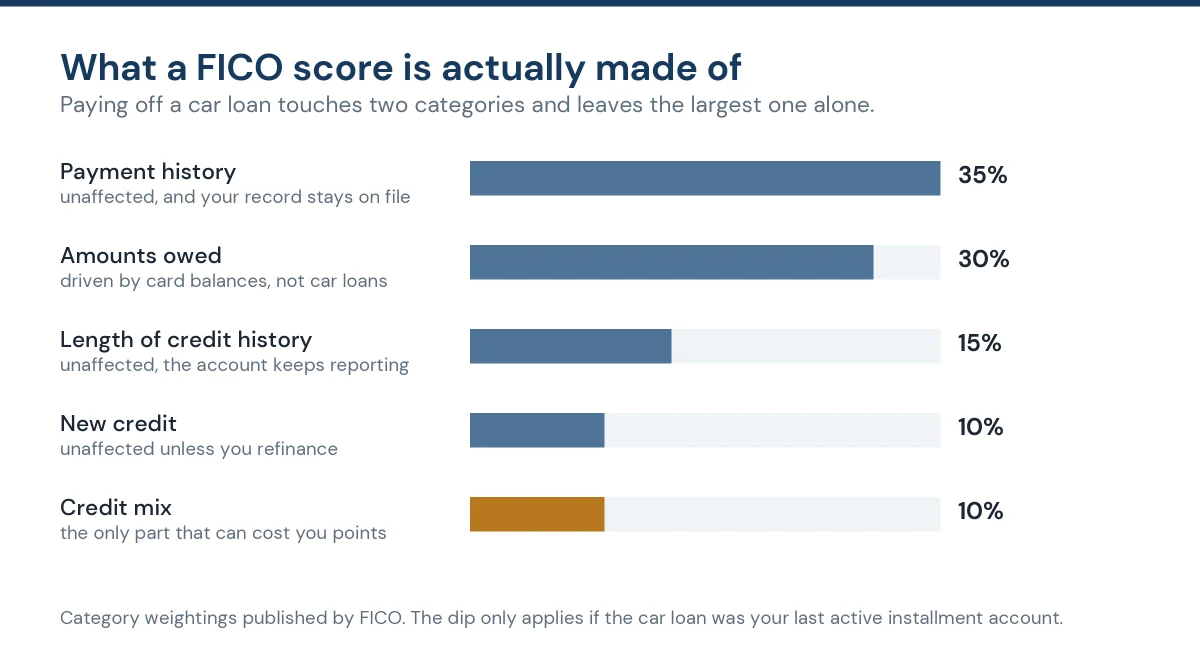
The part almost every guide leaves out is how small the affected ingredient is. Credit mix, the thing people worry about, is 10% of a FICO score. Payment history, which paying off a loan protects, is 35%.
Does paying off a car loan help credit? The short answer
| Your situation | What usually happens |
|---|---|
| You still have a mortgage or another installment loan | Little or no change. Credit mix is unaffected |
| It was your only installment loan | A small, temporary dip is likely |
| You carry credit card balances | No change to utilisation. Card balances drive that, not car loans |
| You are applying for a mortgage | Removing the payment helps your debt-to-income ratio, which the lender also weighs |
| Long term, any of the above | The paid account keeps reporting positively |
What actually changes on your credit file
A FICO score is built from five categories with published weightings. Paying off a car loan touches two of them, and leaves the largest one untouched:
| FICO category | Weight | Effect of paying off your car loan |
|---|---|---|
| Payment history | 35% | None, and your on-time record stays on the file |
| Amounts owed | 30% | Your installment balance falls to zero. Card utilisation is unchanged |
| Length of credit history | 15% | None. The account does not vanish when it closes |
| New credit | 10% | None, unless you refinance and a new account is opened |
| Credit mix | 10% | This is the one that can cost you points, and only if it was your last installment loan |
FICO describes credit mix as its look at “your mix of credit cards, retail accounts, installment loans, finance company accounts and mortgage loans”. A car loan is an installment account. If it is the only one you have, closing it removes that category from your file.
Why the dip happens at all
FICO is direct about it: “paying off the last of your active installment loans can result in a loss of points”. The reason is a detail most articles skip. FICO says that “having a low installment loan balance to loan amount ratio is even less risky than having no active installment loans at all”.
Read that carefully. A car loan you have nearly finished paying is a better scoring ingredient than no car loan at all. You are not being punished for clearing the debt. You are losing a data point that was working in your favour, because a nearly-repaid loan is evidence you manage installment credit well.
That is also why the effect is temporary rather than structural. FICO adds that “even after a consumer has paid off their installment debt(s), it is still possible to have a very high FICO Score, by actively and responsibly managing other types of accounts”.
The myth: it does not shorten your credit history
The most common explanation you will read is that paying off a car loan lowers the average age of your accounts. That is not how credit reports work.
The Consumer Financial Protection Bureau states that “a positive (on-time paid as agreed) payment history on a credit card, mortgage, or other loan may show up on your credit report so long as you are paying your accounts on time, and may be reported after a loan is paid off, and even after the account is closed”.
So the account does not disappear the moment you clear it. It stays, it keeps showing every on-time payment you made, and it keeps contributing to the length of your history. Length of credit history is 15% of your score and paying off a car loan does not take it away.
Who sees a dip, and who does not
- You have a mortgage, a student loan or another car loan. Credit mix is unaffected, because you still hold installment credit. Expect little or no change.
- The car loan was your only installment account. This is the group that sees the dip, usually a handful of points.
- You are rebuilding credit with a thin file. Fewer accounts means each one carries more weight, so the change is more noticeable.
- You carry card balances. Your utilisation does not move, because that is calculated on revolving credit. Paying a card down moves it far more than clearing a car loan does.
When paying off a car loan clearly helps
Two things improve immediately, and neither is a credit score.
First, your debt-to-income ratio. The CFPB defines it as “all your monthly debt payments divided by your gross monthly income”, and removing a car payment lowers it straight away. Mortgage lenders weigh that alongside your score, which is why the timing question matters if you are about to apply.
Second, the interest you stop paying. A few score points are worth far less than the money saved on a high-rate loan. Our should I pay off my car loan early test puts a number on that trade, and the early payoff calculator shows the interest and months you would save.
What to do about the paying off car loan early credit score effect
- Check whether it is your last installment loan. If it is not, there is nothing to manage.
- Mind the timing if you are being scored soon. If a mortgage decision is weeks away, ask your loan officer whether they would rather see the payment gone or the score untouched.
- Keep your cards open and low. Amounts owed is 30% of the score, three times the weight of credit mix, and it is driven by revolving balances.
- Do not take out a loan you do not need to protect your credit mix. Paying interest to maintain a 10% category is a poor trade.
- Let it recover. The account keeps reporting positively, and the dip fades as your other accounts age.
If you have not decided whether to clear the loan at all, start with whether you can pay off a car loan early and what it costs, then how to pay off a car loan early without wasting the money. The full route is in our car loan payoff guide.
Moving the balance onto a card changes your utilisation sharply. Paying off a car loan with a credit card explains what that costs.
What moves your score more than the car loan does
Does paying off a car loan help credit more than the alternatives? Usually not. If the goal is a higher score rather than a cleared debt, the car loan is rarely the best lever. Amounts owed is 30% of a FICO score, three times the weight of credit mix, and the part that moves hardest is revolving utilisation: how much of your card limits you are using.
| Balance on a $12,000 card limit | Utilisation | How it is generally read |
|---|---|---|
| $10,000 | 83% | Heavily extended |
| $3,600 | 30% | Moderate |
| $1,200 | 10% | Low |
Moving from 83% to 10% on that card changes a 30% category. Clearing your last car loan changes a 10% category, in the wrong direction. If you have the same money available for either, the card almost always does more for the score.
When the change actually shows up
Nothing happens the moment your payment clears. Lenders report to the credit reference agencies on their own cycle, usually monthly, so the account will keep showing a balance until the next report goes out. Two consequences follow.
- Any dip arrives late. If you clear the loan today, the change may not reach your file for several weeks, and the different agencies will not update on the same day.
- Timing a mortgage application is guesswork. You cannot reliably clear a loan and have the file updated by a specific date, which is another reason to ask the lender rather than trying to engineer it.
Check your report a month or so afterwards and confirm the account shows as closed and paid, with no balance and no missed payments. Errors at this stage are worth correcting straight away.
Paying it off before a mortgage application
A mortgage application is the one situation where the decision is genuinely finely balanced, because the two things a mortgage lender looks at pull in opposite directions.
Clearing the loan removes the monthly payment from your debt-to-income ratio, which the CFPB defines as “all your monthly debt payments divided by your gross monthly income”. On a $6,000 monthly income, removing a $560 car payment improves DTI by more than nine percentage points, which can matter more to an underwriter than a handful of score points.
Against that, clearing your last installment loan may cost a few points at exactly the moment you are being scored, and the cash you spend is cash you no longer have for the deposit or closing costs.
The practical answer is to ask your loan officer which constraint your file is tight against. They can see whether you are close to a DTI threshold or a score threshold, and that answer decides it in a minute. Do not guess.
Does paying off a car loan help credit? Four myths worth dropping
- “It shortens my credit history.” No. The CFPB says positive history may be reported after a loan is paid off and even after the account is closed.
- “I should keep a small balance to look active.” On a car loan this means paying interest and keeping a payment on your DTI to protect a 10% category, and a missed payment on that token balance would cost far more.
- “Paying early damages my credit more than paying on schedule.” The effect comes from the account closing, not from closing it early.
- “My score will drop by a set number of points.” It depends entirely on the rest of your file. Anyone quoting a fixed figure is guessing.
Car loan payoff credit score FAQs
Does paying off a car loan help credit?
Long term, yes. The account keeps reporting as paid on time, which supports payment history, the largest FICO category at 35%. Short term you may lose a few points if it was your last active installment loan, because credit mix, worth 10%, loses a category.
How many points will my score drop after paying off a car loan?
There is no fixed number, and anyone quoting one is guessing. The change depends on what else is on your file. If you still hold a mortgage, student loan or another car loan, expect little or no movement. If it was your only installment account, a small dip is likely and it recovers as your other accounts age.
Does paying off a car loan early hurt your credit more than paying it on schedule?
No. The score effect comes from the account closing, not from closing it early. Paying the final instalment two years ahead of schedule and paying it on the last scheduled date affect credit mix the same way.
Does paying off a car loan lower my average account age?
No, and this is the most common myth on the subject. The CFPB says positive payment history may be reported after a loan is paid off and even after the account is closed, so the account stays on your report and keeps counting towards the length of your credit history.
Should I keep a small balance on my car loan to protect my score?
It rarely pays. You keep paying interest and keep a monthly payment on your file that counts against your debt-to-income ratio, all to protect a category worth 10% of the score. A missed payment on that token balance would do far more damage than the points you were protecting.
What helps my credit score more than paying off a car loan?
Paying down credit card balances. Amounts owed is 30% of a FICO score, three times the weight of credit mix, and it is driven by revolving utilisation rather than installment loans. On-time payments matter most of all at 35%.
Sources
- myFICO: what’s in your FICO Score (category weightings: payment history 35%, amounts owed 30%, length of history 15%, new credit 10%, credit mix 10%), checked 27 September 2026
- myFICO: can paying off loans lower your FICO Score? (installment balance to loan amount ratio), checked 27 September 2026
- CFPB: how long does information stay on my credit report? (positive history reported after payoff and after closure), checked 27 September 2026
- CFPB: what is a debt-to-income ratio?, checked 27 September 2026
This guide is general information, not financial advice. Scoring models differ, and FICO and VantageScore weigh the same file differently, so your own movement may not match the pattern described here.
Written by Nimra Saleem for MoneyMentorDesk.com. Last reviewed on 27 September 2026 against FICO’s published scoring guidance and CFPB consumer guidance.
Pingback: Can You Pay Off Car Loan With Credit Card? 4 Real Options
Pingback: Car Loan Payoff: The Complete Guide in 4 Stages
Pingback: Refinance Auto Loan Calculator: 3 Terms, 1 Real Answer