
Part of our guide: What Is a 10-Day Payoff Quote? Auto Loan Payoff Explained
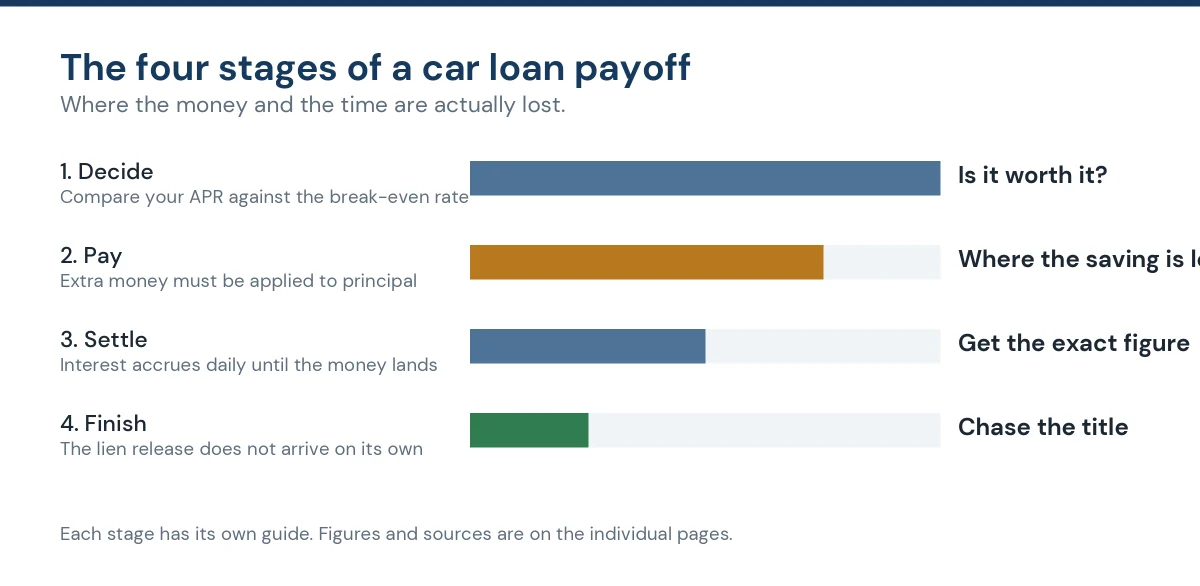
Car loan payoff, or auto loan payoff as US lenders often write it, has four stages: deciding whether early payoff pays, making extra payments land on the principal, settling the exact figure, and getting the title into your name. This page is the map. Every link below goes to a guide built on primary sources, and the two tools run the numbers for your own loan.
Before you borrow, how to calculate the total cost of a car loan has a calculator for the monthly payment, the finance charge and the total purchase cost.
Car loan payoff: the six facts that decide everything
| Fact | Why it matters | Source |
|---|---|---|
| You may prepay, and unearned interest must be refunded | No federal law stops you clearing the balance early | 15 U.S.C. § 1615 |
| Above 61 months the refund method is fixed by law | Rules out the Rule of 78s on long loans | 15 U.S.C. § 1615 |
| Your contract must disclose a prepayment charge | The wording also tells you which interest type you have | Regulation Z § 1026.18(k) |
| Extra payments do nothing on a precomputed loan | Only settling in full saves you money there | CFPB |
| Payments go to fees, then interest, then principal | Extra money does not reach the balance automatically | CFPB |
| Clearing your last installment loan can cost score points | Timing matters if you are about to be credit-checked | FICO |
Stage 1: Decide whether to pay it off early
The arithmetic is not a straight comparison of your APR against your savings rate. Your loan balance shrinks every month while cash keeps earning on the full amount, so the APR has to be roughly double the rate your cash earns before keeping the money wins.
- Should I pay off my car loan early? A five-question test, the break-even rate for your remaining term, and an interactive version of the test.
- Can you pay off a car loan early? What the law allows, prepayment penalties, what your state adds, and the military rule that is narrower than it looks.
- When to refinance, and when to wait The middle path if the rate is the problem rather than the term.
Stage 2: Do it without wasting the money
Stage two is where most of the saving is lost. Extra money sent without instructions is often applied as next month’s payment rather than to the principal, which advances your due date and saves you nothing.
- How to pay off a car loan early Six steps, what each method saves on a worked example, and how to make sure the extra reaches the principal.
- Car loan early payoff calculator Enter your balance, rate and payment to see the months and interest an extra amount would save.
Stage 3: Get the car loan payoff figure right
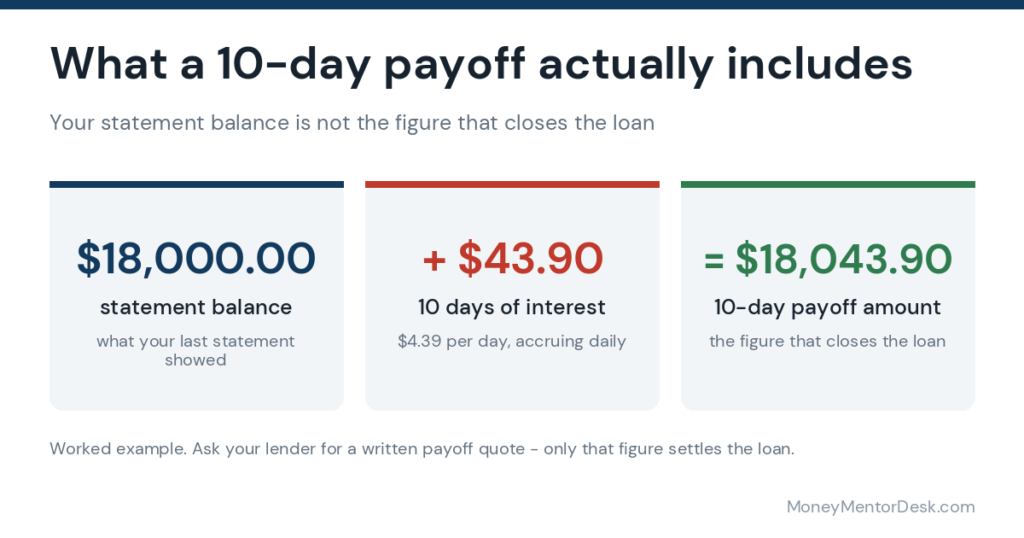
The balance in your banking app is not what closes the loan. Interest accrues daily until the money reaches the lender, so lenders quote a figure that is good for a set number of days, usually ten.
- What is a 10-day payoff quote? What the figure includes and why it is higher than your balance.
- How to calculate your 10-day payoff amount Work it out yourself so you can check the lender’s number.
- How to request a 10-day payoff letter Four ways to get one, and which is fastest.
- 10-day payoff letter example How to read every section of the letter when it arrives.
Stage 4: Finish the paperwork
A car loan payoff is not finished when the payment clears. It is done when the lien is off the title and the title is in your name, and that does not happen on its own.
- Lien release after car payoff How long it takes, a state quick-reference table, and a checklist for chasing it.
Which car loan payoff guide do you need?
| If you are asking | Start here |
|---|---|
| Is paying this off early even worth it? | The five-question test |
| Am I allowed to, and will they charge me? | What the law allows |
| How much would I actually save? | The calculator |
| How do I make extra payments count? | The six steps |
| What exact figure closes the loan? | Calculating the payoff amount |
| Where is my title? | Lien release after payoff |
Reshaping the loan rather than clearing it? The auto refinance calculator compares your current loan against an offer.
On the credit question specifically, see does paying off a car loan help credit.
Thinking of putting it on plastic? Can you pay off a car loan with a credit card works through the four routes and what each one costs.
Car loan payoff FAQs
What does car loan payoff mean?
It means clearing the remaining balance of your auto loan so the debt is closed and the lender releases its lien on the vehicle. The payoff amount is usually higher than the balance shown in your app, because interest accrues daily until the money reaches the lender.
How do I find my exact car loan payoff amount?
Ask the lender for a payoff quote, which is valid for a set number of days, usually ten. You can also calculate it yourself from your balance, APR and the number of days until payment, then check the lender’s figure against yours.
Is it worth paying off a car loan early?
It depends on whether your APR beats the break-even rate for your remaining term. Because the loan balance shrinks while cash earns on the full amount, the APR has to be roughly double what your cash earns. Against an ordinary savings account paying 0.37%, the 24-month break-even is about 0.71%, so paying off usually wins.
Do extra payments reduce my car loan principal automatically?
No. The CFPB says payments go first to any fees due, then to interest, then to principal, and you may need to ask for extra money to be applied to the principal. Check the next statement to confirm the balance fell rather than your due date moving forward.
How long does it take to get the title after paying off a car loan?
It varies by lender and state, and ranges from a couple of weeks to around two months. Some states hold titles electronically and require you to request a paper copy. Published lender timeframes and a state quick-reference table are in our lien release guide.
Car loan payoff: what each mistake actually costs
Every stage has one expensive way to get it wrong. These are the figures from the guides below, on realistic balances:
| Mistake | What it costs | Where it is covered |
|---|---|---|
| Paying extra on a precomputed loan | Nothing gained at all. The CFPB says extra payments there do not reduce principal or interest | Deciding and paying |
| Sending extra money without instructions | The due date moves forward instead of the balance falling, so the interest saving never happens | Stage 2 |
| Refinancing at the wrong term | $669 more on an $18,000 balance, despite a lower rate | Refinance calculator |
| Paying the app balance instead of the payoff quote | The loan stays open over a few dollars of accrued interest | Stage 3 |
| Not chasing the lien release | Weeks of delay, and you cannot sell the car until the title is clear | Stage 4 |
| Moving the balance to a credit card | $1,529 more over 24 months at average rates | Credit card guide |
How long each stage takes
Timings vary by lender and by state, but the shape is consistent, and knowing it tells you when something has actually gone wrong rather than just feeling slow.
- Getting a payoff quote: immediate online with most lenders, or a few days by post. The quote is usually valid for about ten days.
- The payment clearing: same day by card or transfer where accepted, several days by cheque. Interest accrues until it lands, which is why the quote carries a date.
- The lien release: published lender timeframes run from about ten business days to six weeks or more.
- The title reaching you: depends on your state, and some states hold titles electronically so you have to request a paper copy.
If a stage runs well past these, chase it in writing rather than by phone, so you have a record. The lien release guide has a checklist and a state quick-reference table.
Car loan payoff terms, in plain English
Lenders use these words as though everyone knows them. They matter because several of them mean different amounts of money.
| Term | What it means |
|---|---|
| Payoff amount | The total that closes the loan on a stated date. Higher than your balance, because interest accrues daily |
| Balance | What you owe right now, before the interest that builds up before your payment lands |
| Per diem | The interest added each day. Balance multiplied by the APR, divided by 365 or sometimes 360 |
| 10-day payoff quote | A payoff figure that stays valid for ten days, so a posted payment still clears the loan |
| Payoff letter | The document setting out the figure, the date it expires and where to send the money |
| Simple interest | Interest charged on the balance you still owe, so extra payments reduce it |
| Precomputed interest | Total interest set at the start. Extra payments do not reduce what you owe |
| Rule of 78s | A front-loaded refund formula. Federal law bars it above 61 months |
| Unearned interest | Interest you were charged for time you no longer hold the loan, refundable on full prepayment |
| Lien | The lender’s legal claim on the car, which has to be released before the title is clear |
| Lien release | The confirmation that the claim has been removed |
| Title | The state document naming the owner. The loan is not truly finished until this is in your name |
The tools, and when to use each
- Early payoff calculator when you want to know what an extra amount each month is worth in interest and months.
- Auto refinance calculator when you have an offer and need to see both the monthly change and the change to the total.
- The decision test inside should I pay off my car loan early when you are weighing payoff against keeping the cash.
- The per-diem calculator inside how to calculate your 10-day payoff amount when you want to check the lender’s figure.
If you are in the UK
Everything above covers US car loans. UK car finance works differently: agreements are usually PCP, hire purchase or conditional sale, the lender owns the car until the end, and the Consumer Credit Act 1974 gives you statutory rights to settle early and to hand the car back once you have paid half the total price. Start with early settlement of car finance and the UK car finance calculator.
How these guides are researched
Every figure in this cluster is traced to a named source: the United States Code, the Code of Federal Regulations, Regulation Z, state motor vehicle finance statutes, the CFPB, FICO, the FDIC, the US Treasury and Experian. Worked examples are calculated for the article and labelled as ours, with the method stated so you can check them.
Where two sources disagree, both are named rather than one being quietly picked. Where a claim cannot be verified against a primary source, it is left out. Lender timeframes are attributed to the lender that published them, because a lender describes its own procedure rather than your state’s law. See our editorial policy for how corrections are handled.
Sources
- 15 U.S.C. § 1615 (refund of unearned interest on prepayment; actuarial method required above 61 months), checked 30 September 2026
- Regulation Z § 1026.18(k) (prepayment disclosures), checked 30 September 2026
- CFPB: simple interest vs precomputed interest and CFPB: interest or principal first, checked 30 September 2026
- myFICO: can paying off loans lower your FICO Score?, checked 30 September 2026
This guide is general information, not financial or legal advice. Your own contract and your state’s law decide what applies to you.
Maintained by Nimra Saleem for MoneyMentorDesk.com. Last reviewed on 26 September 2026.
Pingback: Refinance Auto Loan Calculator: Saving vs Total Cost
Pingback: How Many Missed Payments Before Repossession? 6 Rules